SKOCH Summit
Mr Rohan Kochhar
Founder, SKOCH Law Offices
Rohan Kochhar stands at the intersection of economics, social science, and law, leveraging his multidisciplinary expertise to drive impactful change in public policy, emerging technologies, and ESG (Environmental, Social, and Governance) initiatives. As the founder of SKOCH Law Offices, Rohan has built a boutique law firm renowned for its deep domain knowledge and innovative approach to legal challenges.
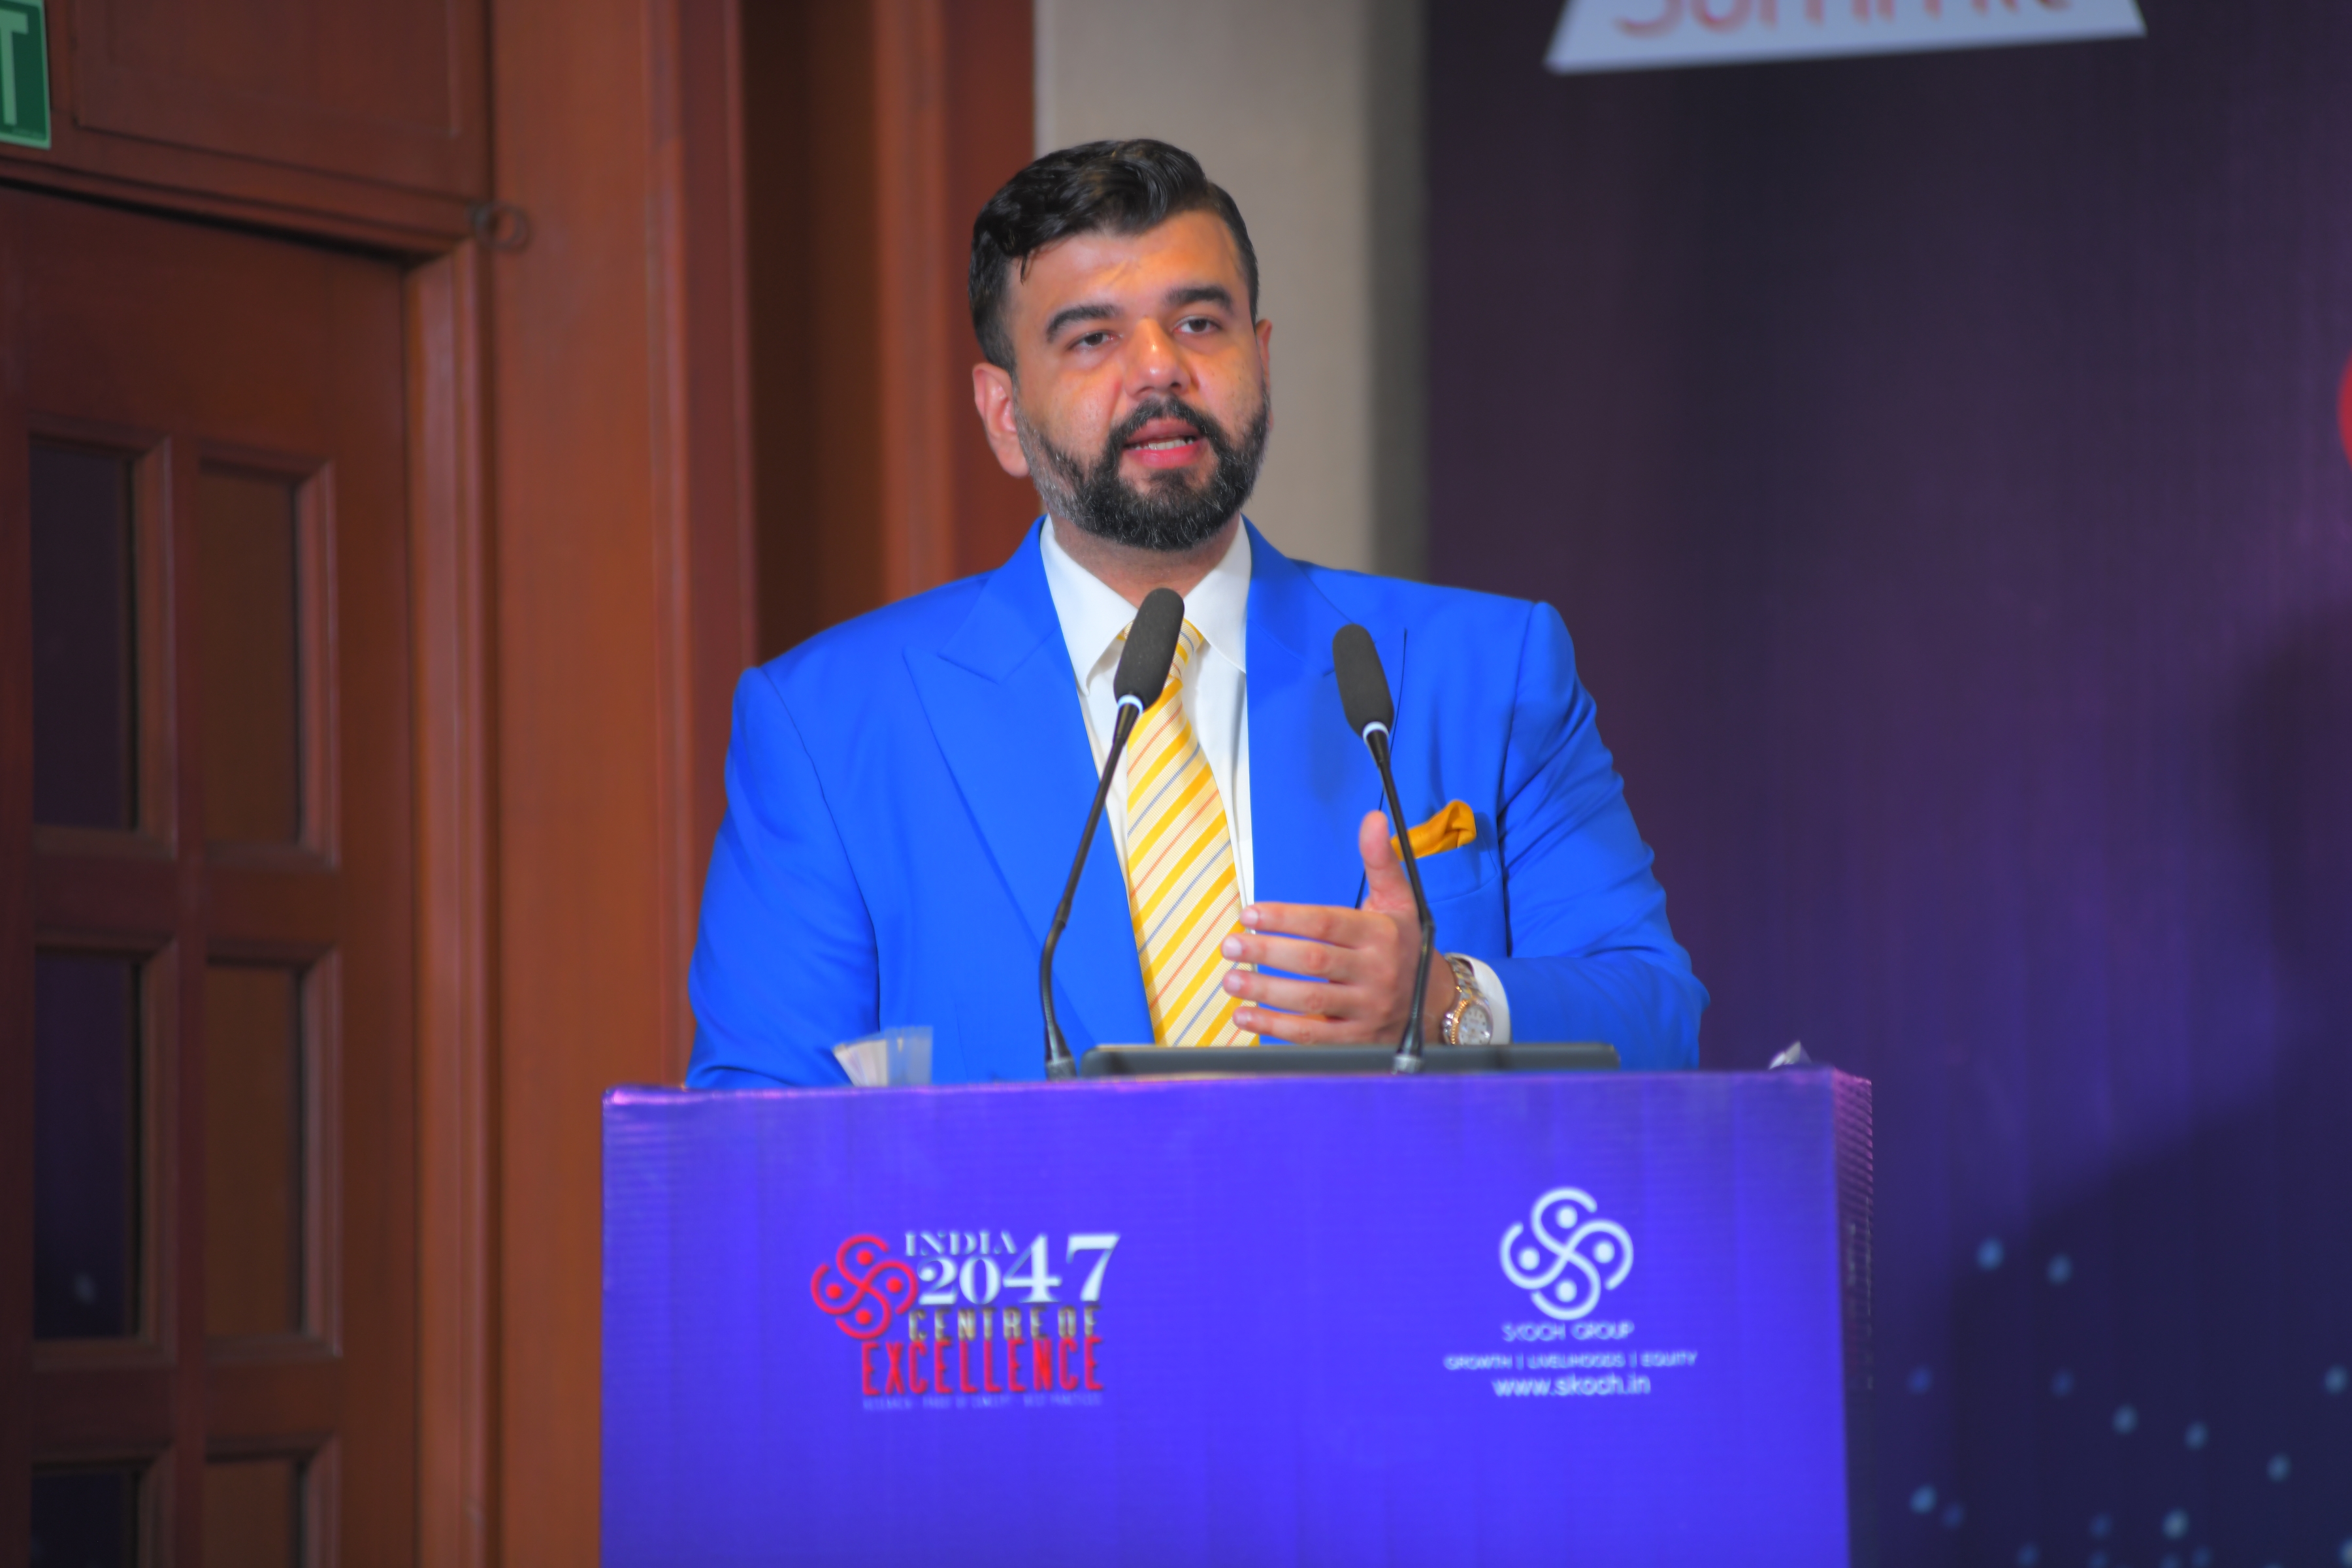
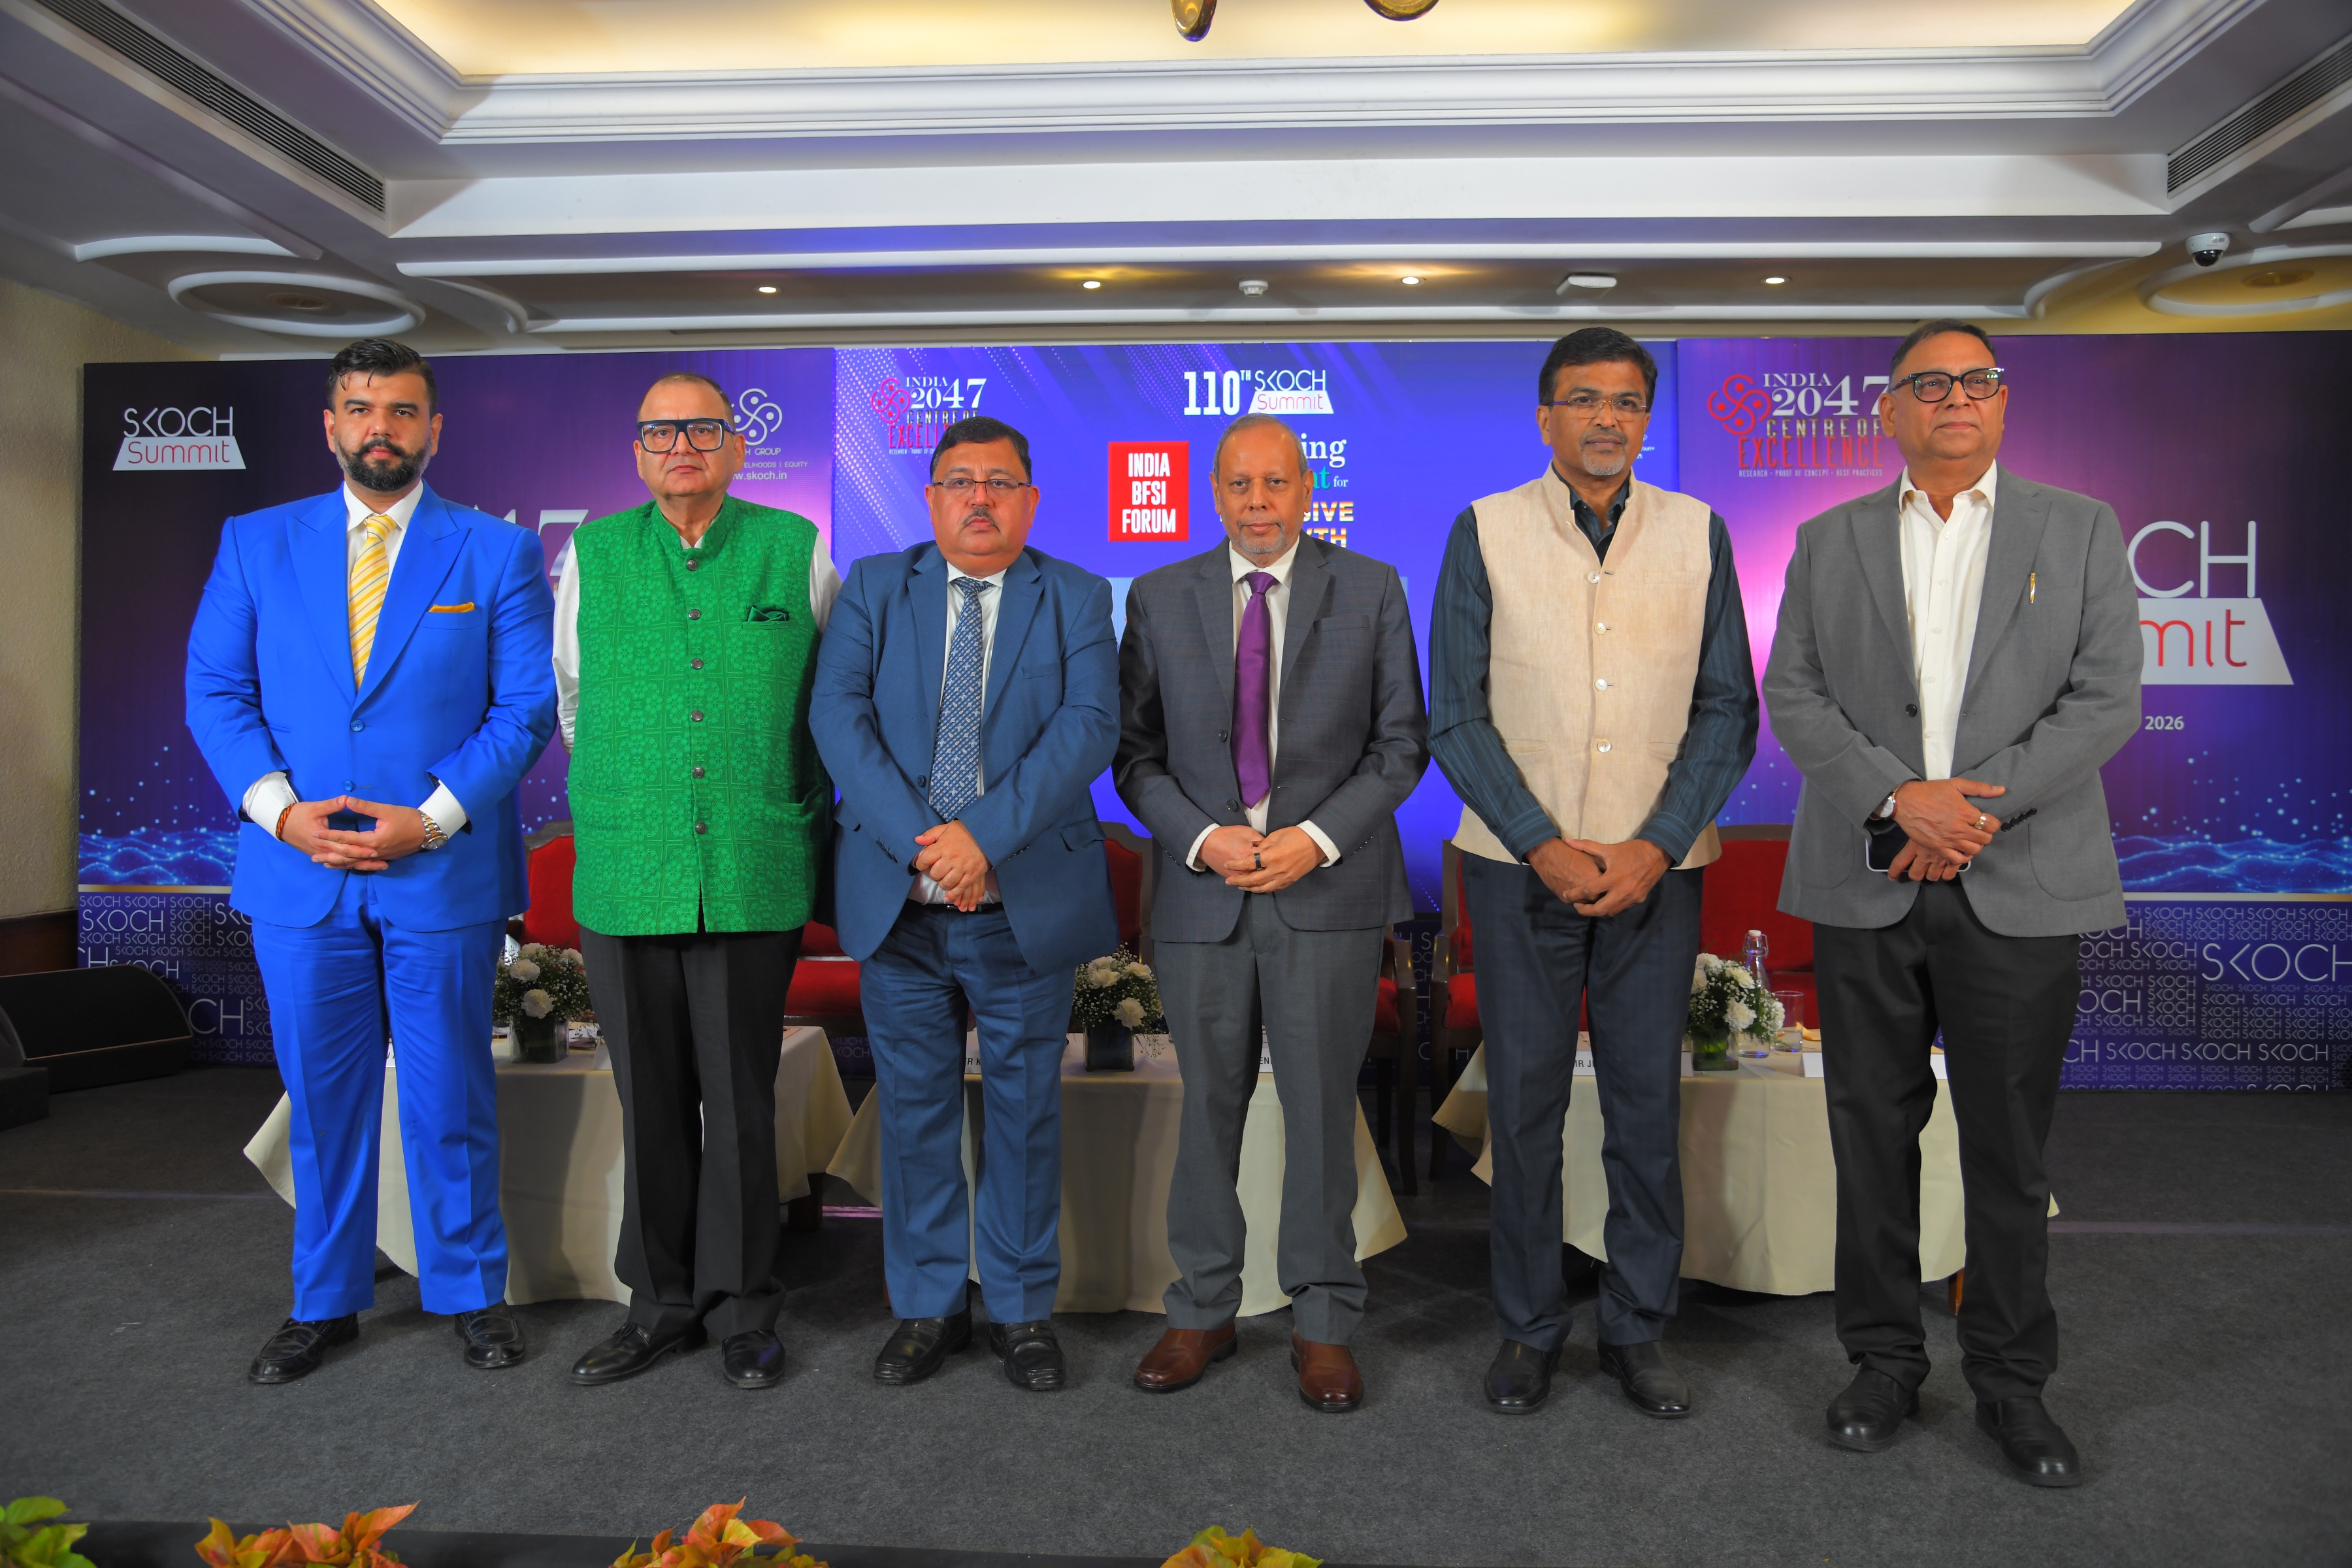
Mr Rohan Kochhar at the 110th SKOCH Summit: Banking Bharat for Inclusive Growth
Mr Rohan Kochhar
Founder, SKOCH Law Offices
Key Points*
- Growth remains the central objective, but India’s next phase of development requires stronger environmental and social foundations such as clean air, safe water, sanitation, resilient cities, sustainable agriculture and ecological security.
- The speaker frames the central question as whether India’s financial system is not only growing in scale but also financing investment, distributing risk and supporting productivity.
- He argues that financial deepening should be judged by function, not simply by the size of markets or financial assets.
- He defines functional financial depth as finance that reaches firms across sizes, converts household savings into patient capital, supports long-term investment and preserves stability.
- He explains that balanced financial deepening requires both financial institutions and financial markets to work together.
- He notes that India’s financial deepening has been uneven, with equity markets expanding much faster than institutional finance.
- He highlights that most of the rise in the financial deepening index has come from market capitalization and stock trading.
- He points out that higher valuation and trading activity do not automatically prove new capital formation, wider credit access or stronger investment financing.
- He observes that mutual funds and pension assets have expanded strongly, while private sector credit as a share of GDP has weakened.
- He emphasizes that weaker private credit matters particularly for MSMEs and smaller firms that depend more heavily on institutional lending.
- He describes India’s financial market deepening as overwhelmingly equity-led, while corporate and other debt markets have shown relatively limited progress.
- He notes that insurance penetration and institutional risk protection have not kept pace with the expansion of financial markets.
- He argues that financial depth can support growth only when regulation and supervision keep pace with market expansion.
- He identifies enforceable lending and bond recovery as the first major regulatory priority, including faster insolvency resolution and stronger collateral systems.
- He identifies administrative velocity as another priority, calling for faster and more digitized financial approval processes.
- He stresses that supervisory capacity must extend beyond banks to NBFCs, funds and insurers as financial markets deepen.
- He calls for household savings to be converted into long-term patient capital through better pension coverage, portability, suitability standards and stronger disclosure.
- He summarizes the next stage of reform as a shift from financial scale to financial function.
- He concludes that markets, banks, pensions, insurance and bonds all matter, but each channel must perform its intended economic function.
- For Viksit Bharat, he argues that financial deepening must ultimately mean finance that funds investment, reaches firms across sizes, distributes risk and remains stable.
* This content is AI generated. It is suggested to read the full transcript for any furthur clarity.
Transcript
Honorable ministers, distinguished economists, senior officers, bankers, industry leaders, colleagues and dear friends, I extend a heartfelt and warm welcome to you to the 110th SKOCH Summit. Thank you very much for taking time out and being here with us today at the India Habitat Centre. We're graced by the presence of Dr. S. Mahendra Dev, the gentleman with the responsibility of the Indian economy and at the helm of affairs as far as Indian economic policy is concerned. We're joined by Mr. Lal Singh, Executive Director at the Bank of Baroda, a career and seasoned banker. Mr. G. G. Manin, who has dedicated a lifetime to work in the microfinance sector and currently serves as the head of its self-regulatory body. Mr. Anil Bhardwaj will be joining us shortly. Mr. Sameer Kochar is also with us today.
There was a conversation today about inclusive growth, ladies and gentlemen, and the paper that we present to you is called Financial Deepening in India. The political economy of Viksit Bharat will not be defined only by how much India saves or how large our financial markets become. It will now be defined by a more difficult question: does Indian finance actually finance investment, distribute risk and support productivity? That is the central question of this paper. India has built financial scale quickly. The task is now to ask whether that scale is performing its economic function.
The argument is deliberately not that India lacks financial growth. It doesn't. It is that India has built financial scale quickly. How quickly can we make sure that the scale at which India's businesses have grown redistributes investment and redistributes risk? Financial deepening in the paper therefore means the expansion, diversification and use of instruments and markets relative to the real economy. But the paper also asks the second question: has this depth become functional? That means, does finance reach firms across sizes, convert household savings into patient capital, support long-term investment and preserve stability? That therefore is the structure of the paper that we present today.
Let's get down to the core proposition, ladies and gentlemen. India's financial depth rose 61.9%, but that rise was led almost entirely by equity markets. Function is a separate question. It asks whether that scale finances firms and distributes risk. Balanced deepening requires institutions and markets to work together and we study both through the course of this paper. Therefore we develop two basic buckets. We study financial institutional depth and the depth of financial markets across firm sizes.
The regulatory frontier follows from that diagnosis. We need enforceable lending, we need faster approvals and insolvency resolution, supervising capacity that maps to market depth and incentives that turn household savings into long-term capital. So the paper is not a celebration of market expansion. It is an inquiry into whether financial deepening has become investment-supporting, risk-distributing and stable.
Let's have a quick look at the academic literature on the subject, ladies and gentlemen. Goldsmith in 1969 documented the close association between financial structure and economic development. McKinnon and Shaw in 1973 argued that financial repression, administered rates, directed credit and high reserve requirements discourage savings and fragment capital allocation. King and Levine in 1993 showed that financial development predicts growth, capital accumulation and productivity. Rajan and Zingales in 1998 emphasized that stock market liquidity and banking both matter for long-term growth.
Beck, Levine and Loayza in the year 2000 linked intermediary development especially to productivity growth. And the paper also notes Levine's 2005 synthesis: finance matters when it mobilizes savings, allocates capital, monitors borrowers, manages risk and lowers transaction costs. So the literature doesn't really say more finance is always better. It says finance matters when it performs critical functions.
Depth, ladies and gentlemen, is one singular dimension and that dimension has limits because returns diminish. The World Bank in 2012 developed a framework which separated financial development into two buckets, institutions and markets, and thereafter into four dimensions: depth, access, efficiency and stability. Our paper measures only depth, and that is important. Depth tells us scale and activity. It does not directly measure access, pricing efficiency, consumer protection, resilience or the destination of finance.
The limits are also part of the literature that we would like to share with you. Sahay and others in 2015 showed that beyond a threshold, depth weakens the growth effects unless regulation and supervision keep pace. Arcand and Panizza in 2012 show that the growth effect of private credit weakens and may turn negative at very high depth. There have also been earlier attempts to diagnose this market, ladies and gentlemen. The Patil Committee in 2005 examined corporate bonds and securitisation. The Mistry Committee in 2007 examined Mumbai as an international financial centre. The Rajan Committee in 2008 published its report in 2009 and considered broader financial sector reform. The Khan Working Group in 2016 returned back to the corporate bond market and the Household Finance Committee of 2017 studied Indian household balance sheets.
The recurring diagnosis is stable. We have thin secondary trading in corporate bonds, low floating stock, household wealth is still heavily concentrated in physical assets and there is a large gap between diagnosis and implementation. Nine indicators, ladies and gentlemen, we present to you today in two equally weighted blocks. The financial institution block includes mutual fund assets under management, pension fund assets under management, insurance premiums and private sector credit as a percentage of GDP. The financial markets block includes stock market capitalisation, stocks traded, international government debt securities, non-financial corporate debt securities and financial corporate debt securities. The weights are adapted from Sahay's work in 2015 and the World Bank report of 2012.
The reading rule is therefore transparent. A one-point rise in market capitalisation adds 0.125 to the composite and a one-point rise in private credit adds 0.135. The important caveat is that inputs are not normalised. So indicators with large ranges, especially market capitalisation and so on, can dominate the composite, and that caveat becomes central to our results.
If you look at the financial institution bucket, ladies and gentlemen, I'm sure you can see we have mutual fund assets under management, pension fund assets under management, insurance premiums and private sector credit, and all of these are expressed as a percentage of GDP. The headline result therefore, ladies and gentlemen, as per our analysis, is clear: India's composite financial deepening index rose from 23.43 in 2013-14 to 27.93 in 2024-25.
That is a 61.9% increase, but the sub-indices behave very differently. The financial markets sub-index rose 92.7% from 30.20 to 58.18 and the financial institution sub-index rose only 6.1% from 16.66 to 17.63. Therefore, the central empirical finding is not simply that India deepened financially. It is also that India's financial markets deepened unevenly and market depth expanded sharply, while institutional depth, credit, insurance, risk pooling and balance sheet intermediation remained broadly flat.
If we look at the decomposition of this contribution, it becomes evident why this happens. The composite rose by 14.5 points. Of that rise, 94.2% came from just two indicators of the nine that we presented to you, and that is market capitalization and stocks traded. Market capitalization contributed 7.35 points and stocks traded contributed 6.30 points. Mutual funds contributed 1.57 points, pension funds 0.45 points, non-financial corporate debt only 0.34 points. Private sector credit contributed minus 1.52 points.
The final year in question reinforces this point. Stocks traded supplied 3.69 out of 4.01 points gained in 2024-25 while market capitalization slipped slightly. This means the index has captured valuation and turnover, and those are real forms of depth, but they do not themselves prove primary issuance, new capital formation or wider credit access. So scale has risen. Function has to be studied and treated separately.
Let's look at the financial institution block. This tells a mixed story. Mutual fund assets under management rose to 19.88% of GDP from 7.35%, which is a 170.6% increase or 9.47% compounded annually. Pension fund assets rose more than tenfold from 0.43% to 4.34% of GDP, growing at 23.4% annually. Private sector credit is the weak trend. It fell to 40.02% of GDP from 51.3%, which is a fall of 11.28 percentage points. Because private credit carries the largest institutional weight, its fall nearly cancels the gains in mutual funds and pensions.
This matters because smaller firms still rely on private sector credit. Now if we look at financial markets, the market block is much stronger but it is also concentrated. Stock market capitalization rose to 137.72% of GDP in 2024-25 from 78.89% in 2013-14. Stocks traded rose from 30.8% to 85.6% of GDP, which is a recorded increase of 177.9%, ladies and gentlemen. The markets block accounts for 96.5% of the composite gain. But bond components moved little.
International government debt was 4.3% of GDP against 4.5% in 2013-14. Some might argue that's a good thing. Non-financial corporate debt was 7.92% from 5.23%, still below its 9.26% peak. Financial corporation debt was 8.3% from 8.2%, below 10.17% in 2017-18. So this is market-led deepening and within that it is overwhelmingly equity-led. The open question therefore still remains: is equity depth converting itself into capital formation in the Indian markets?
Now there was a discontinuous year in our analysis and that was the pandemic year. If we look at the pandemic-year discontinuity, ladies and gentlemen, we must see that the index jumps to 32.74 in 2020-21 after being 26.13 in 2019-20. Stocks traded rose to 68.9% of GDP from 42.60%. Mutual fund assets rose and pension fund assets also increased. The paper does not over-interpret this as structural reform.
It could reflect portfolio reallocation, denominator effects from nominal GDP and valuations responding quickly to liquidity. So 2020-21 at best is read as a combined macro-financial episode. When scale, ladies and gentlemen, grows faster than function, the problem that arises is as follows.
The constraint sits in credit and insurance. Private sector credit was above 51% of GDP before the 2016-17 step, then dropped to the high 30s and ended at 40.02%. Part of that step may be a break in the data. It may be an anomalous year. But at the same time, the 2015 asset quality review exposed balance sheet stress and gross NPAs rose to 11.2% by 2018 from about 4.3%.
Insurance also tracks GDP rather than showing structural deepening. Life premiums fell from 2.8% to 2.68% of GDP and non-life rose from 0.69% to 0.93%, and total penetration remains broadly flat. So the institutional base, which is the MSMEs, the smaller firms and households needing risk protection, has not really kept pace with the markets.
So therefore, while the index reports market deepening, whether the deepening adds financing for investment continues to be a separate question. The reallocation explanation, ladies and gentlemen, really falls short. What can reallocation deliver? Reallocation can deliver deeper liquidity, better price discovery and wider distribution of risk. But at the same time, beyond thresholds, the gains from deepening depend on the quality of regulation and supervision.
There are four fronts on the regulatory frontier that we present to you, ladies and gentlemen. The first is appropriability. Lending and bond recovery must be enforceable. That requires faster insolvency resolution, stronger collateral registries, cash-flow underwriting for small firms and better recovery for bondholders.
The second is administrative velocity. Financial capital needs to move faster, and that means digitized approval chains, deemed approvals where risk is low, and a functional repo market with a priceable yield curve.
The third is institutional capacity. Supervising capacity must match market depth. Stress tests must extend beyond banks to NBFCs, to funds and to insurers.
And the fourth is incentive alignment. Household savings must become patient capital. That means pension coverage, portability, annuitisation, suitability standards, and disclosure for funds and insurance, covering claims and not only premiums.
And the intended result, therefore, is financial depth that finances investment, distributes risk and preserves stability in the markets. Our last slide therefore, ladies and gentlemen, speaks about moving from scale to function.
India has demonstrable scale. We've built that financial scale. The task now is to make sure that that scale performs its functions. That means four things, as far as the research is concerned. The first is secure and enforceable lending and bond recovery. The second is faster approvals and working debt-market infrastructure.
The third is supervising capacity that keeps pace with the expanding market depth. And the fourth is household savings being channelled into patient capital. The paper's arguments are not, therefore, anti-market, and they are certainly not tax-centric. They are functional. Markets matter. Banks matter. Pensions matter. Insurance matters. Bonds matter.
But each channel must do what it is meant to do. For Viksit Bharat, financial deepening cannot only mean higher valuations or more turnover. It must mean finance that funds investment, reaches firms across sizes, distributes risk while remaining stable. And that, ladies and gentlemen, is the next regulatory frontier.
With that, I thank you all very much for giving me a patient hearing, and I'd like to invite Mr. Sameer Kochar, Chairman of SKOCH Group, who I have the privilege of assisting in authoring this paper as a research assistant. Thank you very much.